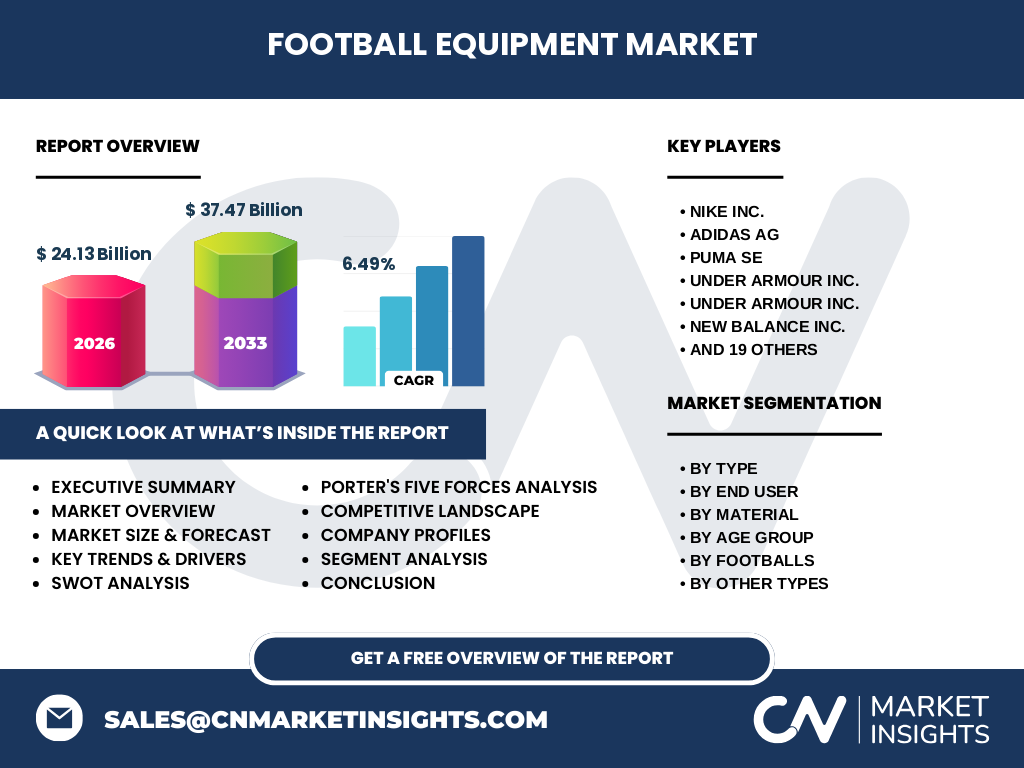
Market overview of the Football Equipment Market
The Football Equipment Market encompasses the design, manufacturing, and distribution of gear vital for soccer and gridiron football. Valued at $24.13 Billion in 2026, this sector spans footwear, apparel, protective gear, and balls. It operates under strict safety protocols enforced by governing bodies like FIFA and NOCSAE, relying heavily on synthetic polymers, high-grade leather, and advanced polyurethane materials.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Our analysis indicates that rising grassroots participation and televised league viewership act as primary growth catalysts. Conversely, stringent material safety compliance and volatile crude oil prices impacting synthetic rubber and polyurethane costs serve as notable restraints. Opportunities abound in smart wearable integration within Firm Ground (FG) Cleats and eco-friendly bio-based materials.
Emerging trends and growth patterns in the Football Equipment Market
The shift toward customization and sustainable production dominates current industry trends. Manufacturers are increasingly utilizing recycled ocean plastics for Team Kits and training wear. Furthermore, the integration of NFC chips into Match Footballs for real-time telemetry tracking represents a transformative growth pattern favored by elite clubs.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted supply chains originating from manufacturing hubs in Southeast Asia, leading to inventory deficits for protective gear and footwear. However, the post-pandemic recovery trajectory has been exceptionally robust, fueled by the reopening of stadiums, resumption of amateur leagues, and a surge in direct-to-consumer digital retail channels.
Competitive landscape and strategic market dynamics
The competitive landscape features a mix of multinational giants like Nike Inc. and Adidas AG alongside specialized protective equipment makers such as Riddell Sports Group and Xenith LLC. Market concentration is high in apparel and footwear, while protective gear exhibits niche fragmentation driven by proprietary helmet safety technologies and concussion-prevention patents.
Executive summary of the Football Equipment Market
Our comprehensive research projects the Football Equipment Market to expand from $24.13 Billion in 2026 to $37.47 Billion by 2033, registering a solid 6.49% CAGR. Growth is anchored by technological innovations in protective gear, surging demand across youth demographics, and expanding digital distribution infrastructure.
Market forecast from 2027 to 2033
Driven by compounding participation rates and rising disposable incomes in emerging economies, the market trajectory scales steadily toward the $37.47 Billion valuation by 2033. This consistent 6.49% CAGR reflects sustained capital expenditure in lightweight, injury-mitigating materials and expanding e-commerce penetration.
Segmentation analysis across product, end-user, material, and age categories
The market segments by Type (Apparel, Shoes, Balls, Protective Equipment), End User (Professional, Recreational), Material (Leather, Synthetic, Rubber), and Age Group (Adults, Youths, Kids). Sub-segments like Shin Guards and Artificial Ground (AG) Cleats drive specialized revenue streams tailored to specific playing surfaces.
Regional market analysis and geographic performance
Geographic distribution highlights Europe and North America as dominant revenue generators due to deeply entrenched club structures and high per-capita spending on sports gear. Meanwhile, the Asia-Pacific region exhibits the fastest-growing adoption rate, propelled by government grassroots sports initiatives and expanding urban retail infrastructure.
In-depth regional review of high-potential territories
North America exhibits high demand for gridiron-specific protective equipment, while Europe heavily consumes soccer-focused footwear and Jerseys. Logistical operations heavily leverage major trade gateways such as the Port of Los Angeles and the Port of Rotterdam to manage inbound inventory from key manufacturing centers in Vietnam and China.
Company profiles and strategic positioning of leading players
Industry leaders leverage distinct competitive moats. Adidas AG and Nike Inc. dominate global apparel and footwear through high-profile athlete endorsements. Simultaneously, innovators like Schutt Sports Group and Kroko LLC focus on advanced impact-absorption technologies to capture institutional and professional league contracts.
Porter's Five Forces analysis of the industry
Supplier power remains moderate due to standardized raw material inputs like polyurethane and rubber. However, buyer power is high given the abundance of alternative brands. Threat of substitution is low for specialized gear, whereas competitive rivalry is intensely fierce among top-tier athletic brands vying for marketing supremacy.
SWOT analysis of the Football Equipment Market
Strengths include strong brand loyalty and advanced material science capabilities. Weaknesses involve vulnerability to counterfeit merchandise and high marketing overheads. Opportunities lie in emerging digital fitness ecosystems, while threats include regulatory scrutiny over head injuries and macroeconomic inflationary pressures affecting consumer discretionary spending.
Value chain analysis from raw materials to end-users
The value chain initiates with petrochemical refiners and leather tanneries supplying raw inputs. Component manufacturers mold synthetic polymers for Shin Guards and Mouthguards, followed by assembly in low-cost labor regions. Distribution flows through wholesale logistics to offline sporting goods stores and online e-commerce platforms.
Investment insights and high-potential areas
Investors should target niche innovators specializing in concussion-reduction technologies and biodegradable athletic textiles. Companies embracing omnichannel inventory models and direct-to-consumer digital apps demonstrate superior margin resilience, making them prime candidates for venture capital and private equity deployment within this expanding sector.
Conclusion and key takeaways for stakeholders
The Football Equipment Market presents compelling growth avenues, backed by a projected climb to $37.47 Billion by 2033. Stakeholders must prioritize sustainability, regulatory compliance, and smart-gear integration to capture market share in an increasingly sophisticated competitive environment.
Research methodology behind our market estimates
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives of brands like Puma SE and Under Armour Inc., and secondary macroeconomic indicators from sports federation databases to ensure absolute accuracy and reliability.
Scope of the report and analytical boundaries
This report covers global revenue streams across specified product types, materials, age brackets, and distribution channels from 2026 through 2033. Limitations include localized informal grey-market sales which are estimated using secondary econometric models rather than direct transactional tracking.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic acquisitions and eco-friendly product launches. Major players like New Balance Inc. and Mizuno Corporation have formed logistic alliances to optimize Asian supply chains, while introducing biodegradable boot soles to comply with tightening European Union environmental directives.